Author name: kamal

Business Consulting & Management

How to Improve Business Performance: A Practical Management Guide

Business performance does not improve simply because a company sets bigger targets or works longer hours. Strong performance comes from knowing what is slowing the business down, measuring the right results, improving weak processes, and making better decisions consistently. When these areas work together, businesses can increase productivity, control costs, improve customer satisfaction, and create stronger financial results. Improving business performance therefore requires a practical management approach. Instead of trying to fix everything at once, identify the areas creating the greatest operational or financial impact, set measurable objectives, assign responsibility, and review progress regularly. Key Takeaways Define business performance using financial, operational, customer, and employee measures. Identify the root causes behind weak results before introducing new solutions. Set specific performance objectives that managers and employees can act on. Improve inefficient processes instead of simply asking teams to work harder. Use KPIs to track progress and identify problems early. Strengthen employee accountability through clear expectations and regular feedback. Use technology to reduce repetitive work and improve access to business information. Review performance regularly and adjust strategies when results fall short. Table of Contents What Business Performance Really Means Where Business Performance Falls Short Set Clear Performance Objectives Measure What Matters Improve Business Processes Strengthen Employee Performance Improve Customer Experience Use Technology Strategically Improve Financial Performance Make Better Management Decisions Create Accountability Across the Business Build a Continuous Improvement Cycle Common Business Performance Mistakes Read More FAQs Final Thoughts What Business Performance Really Means Business performance is broader than revenue or profit. A business can generate strong sales while dealing with rising costs, inefficient operations, high employee turnover, delayed customer service, or weak cash flow. A complete view of performance looks at how effectively the business converts its resources into results. Financial performance shows profitability and cash generation. Operational performance shows how efficiently work is completed. Customer performance reflects satisfaction, retention, and service quality. Employee performance shows productivity, engagement, and the ability of teams to meet expectations. These areas are connected. Poor processes can increase operating costs. High employee turnover can reduce productivity. Slow customer service can affect retention and revenue. Understanding these connections gives management a clearer picture of where improvement is actually needed. Where Business Performance Falls Short Before changing strategies, management needs to understand why performance is below expectations. The visible problem is not always the real problem. Rising Costs Costs can increase through inefficient purchasing, excessive manual work, poor resource planning, overtime, unnecessary software, or process duplication. Reviewing expenses by department and activity can reveal where money is being consumed without producing enough value. Low Productivity Low productivity is not always an employee problem. Employees may be spending significant time waiting for approvals, entering the same information into multiple systems, correcting errors, or completing tasks that could be automated. Weak Sales Conversion A healthy pipeline does not automatically produce revenue. If prospects are not converting, management needs to examine lead quality, pricing, sales follow-up, customer objections, sales processes, and the overall buying experience. Poor Customer Retention Businesses can lose significant revenue by focusing entirely on acquiring new customers. Complaints, slow response times, inconsistent service, unclear communication, and unresolved problems can all reduce retention. The objective is to identify the underlying cause rather than treating the symptom. Set Clear Performance Objectives Once performance gaps are identified, convert them into specific objectives. “Increase productivity” is too broad to guide action. A stronger objective might be to reduce order-processing time by 20% within six months or reduce invoice errors by 30% during the next quarter. Clear objectives give teams a defined target and allow management to determine whether an improvement initiative is producing results. Objectives should also connect with broader business priorities. If the company needs stronger cash flow, reducing unnecessary expenses and shortening payment cycles may matter more than increasing website traffic. If growth is the priority, sales conversion, customer acquisition, capacity, and retention may receive greater attention.   Measure What Matters Performance measurement becomes useful when businesses track indicators that support decisions rather than collecting numbers simply because they are available. Financial measures such as revenue, gross margin, operating profit, cash flow, accounts receivable, and cost levels provide a view of financial health. Operational measures can include turnaround time, production output, error rates, order completion, or capacity utilization. Customer and workforce measures can add another layer of insight. Depending on the business, useful indicators may include: Customer retention and repeat purchases Customer acquisition cost Complaint resolution time Employee turnover Absenteeism Sales conversion rate Average order value The right KPIs depend on the company’s business model. A manufacturing company, professional services firm, retailer, and technology company should not use an identical performance dashboard. Improve Business Processes One of the most effective ways to improve performance is to examine how work actually moves through the business. Remove Unnecessary Steps Processes often become complicated over time. New approvals, spreadsheets, forms, and handoffs are added to solve individual problems, but the overall workflow becomes slower. Map important processes from beginning to end and identify where work is duplicated, delayed, or passed between too many people. Removing unnecessary steps can improve speed without requiring additional staff. Standardize Repetitive Work When similar tasks are completed differently by different employees, quality becomes inconsistent. Standard operating procedures can establish clear expectations for recurring activities such as customer onboarding, purchasing, invoicing, reporting, and service delivery. Standardization also makes training easier because new employees have a defined process to follow. Focus on Bottlenecks A business does not need every process to operate at maximum speed if one major bottleneck continues to restrict the overall workflow. For example, a sales team may generate enough orders to support growth, but if order processing cannot handle the volume, the business may experience delays and customer dissatisfaction. Identifying the constraint allows management to direct resources where they will have the greatest operational impact. Strengthen Employee Performance Employees perform more effectively when they understand what is expected, have the resources to complete their work, and receive timely feedback. Performance management should begin with […]
Real Estate

How Rising Interest Rates Change Commercial Property Valuations

Interest rates are one of the most important external factors affecting commercial property valuations. When borrowing costs rise, the effect can spread across property markets through financing costs, investor return requirements, capitalization rates, transaction activity, and the income expectations attached to individual assets. The relationship is particularly important in the European and U.S. commercial property markets, where changes in central-bank policy and government bond yields can influence investment decisions. However, the effect is not identical across countries, property types, or individual assets. In the U.S., commercial real estate valuations are closely influenced by Treasury yields, financing costs, rental income, and capitalization rates. CBRE’s H1 2026 survey found that U.S. average cap rates remained broadly stable despite higher 10-year Treasury yields, although results varied significantly by property type and market. In Europe, long-term interest rates also remain an important valuation factor. CBRE’s 2026 European outlook notes that elevated long-term rates are limiting the potential for broad yield compression, while the ECB has highlighted the sensitivity of European commercial real estate to medium- and long-term interest rates. Understanding these relationships helps property owners, investors, lenders, developers, and businesses interpret changes in commercial property values. Key Takeaways Rising interest rates can increase property financing costs. Higher required investment returns can put upward pressure on capitalization rates or property yields. Higher cap rates can reduce property values when net operating income remains unchanged. Refinancing can become more expensive when existing loans mature. Higher borrowing costs can reduce the amount investors are willing or able to pay. Strong rental growth can partly offset valuation pressure. The effect varies between the U.S. and European markets. Property type, location, lease quality, vacancy, and debt structure all influence the impact. A higher interest-rate environment does not automatically mean every commercial property will decline in value. Valuation analysis should consider both financing conditions and the property’s underlying income performance. Table of Contents What Is Commercial Property Valuation? Why Interest Rates Matter to Property Values How Interest Rates Affect Capitalization Rates The Relationship Between Cap Rates and Property Values Impact on Commercial Property Financing Effect on Investor Demand Impact on Rental Income and Net Operating Income Refinancing and Existing Property Owners U.S. Commercial Property Valuations European Commercial Property Valuations Differences Between the U.S. and Europe Impact by Property Type How Valuers Assess Properties in a Higher-Rate Environment Strategies for Managing Valuation Pressure Common Commercial Property Valuation Mistakes Commercial Property Valuation Checklist Conclusion FAQs What Is Commercial Property Valuation? Commercial property valuation is the process of estimating the market value of a property based on factors such as income, market conditions, comparable transactions, location, physical characteristics, and investment assumptions. Commercial properties can include: Office buildings Retail properties Industrial facilities Warehouses Logistics properties Hotels Multifamily properties Data centres Mixed-use buildings Different valuation methods may be appropriate depending on the property. For income-producing commercial real estate, the income approach is particularly important. Investors and valuers may consider the property’s net operating income, expected rental growth, vacancy, operating costs, risk, and required investment return. Why Interest Rates Matter to Property Values Interest rates affect commercial property valuations through several channels. The first is financing cost. When interest rates increase, borrowing money to acquire or refinance property generally becomes more expensive. The second is investor return requirements. Investors compare property returns with other investment opportunities, including government bonds and other fixed-income assets. If risk-free or lower-risk yields rise, investors may require greater returns from commercial real estate. The third is capitalization rates. A simplified valuation relationship is: Property Value = Net Operating Income ÷ Capitalization Rate For example, if a property produces annual net operating income of $1 million: Cap Rate Illustrative Property Value 4% $25 million 5% $20 million 6% $16.67 million 7% $14.29 million The example shows why even a relatively small change in the cap rate can have a significant effect on an income-producing property’s indicated value. How Interest Rates Affect Capitalization Rates Capitalization rates, commonly called cap rates in the U.S. and often referred to as yields in European property markets, represent the relationship between a property’s income and its value. When interest rates rise, investors may demand higher returns to compensate for increased financing costs and the changing opportunity cost of capital. This can place upward pressure on cap rates. However, the relationship is not one-to-one. Property values are influenced by several factors at the same time, including: Rental growth Vacancy Property quality Location Tenant strength Lease length Market liquidity Financing availability Risk perception Supply and demand CBRE has previously estimated an econometric relationship in which a 100-basis-point increase in long-term interest rates was associated with a 60-basis-point increase in commercial real estate capitalization rates. This is an analytical relationship, not a fixed rule that applies to every property or market. The Relationship Between Cap Rates and Property Values The relationship between cap rates and property values can be illustrated using a simple example. Suppose a commercial property generates $500,000 in annual net operating income. At a 5% cap rate: $500,000 ÷ 0.05 = $10 million If the required cap rate increases to 6%: $500,000 ÷ 0.06 = $8.33 million The property’s indicated value would therefore fall by approximately 16.7% if income remained unchanged. This is why interest-rate movements can create significant valuation changes even when the physical property itself has not changed. In practice, however, professional valuation considers many additional factors rather than relying on a single cap-rate calculation. Impact on Commercial Property Financing Higher interest rates can increase the cost of acquiring commercial property. For example, a property investor using debt may experience: Higher interest payments Lower cash flow after debt service Reduced debt-service coverage Lower leveraged returns Greater refinancing costs More conservative lending terms This can affect the price buyers are willing to pay. If financing becomes substantially more expensive, an investor may need a lower purchase price to achieve the same target return. European borrowers have also experienced changes in financing costs. The ECB reported that the composite cost of borrowing for new loans to […]

AI Consulting & AI Services

How to Build a RAG System Using a Company’s Internal Knowledge

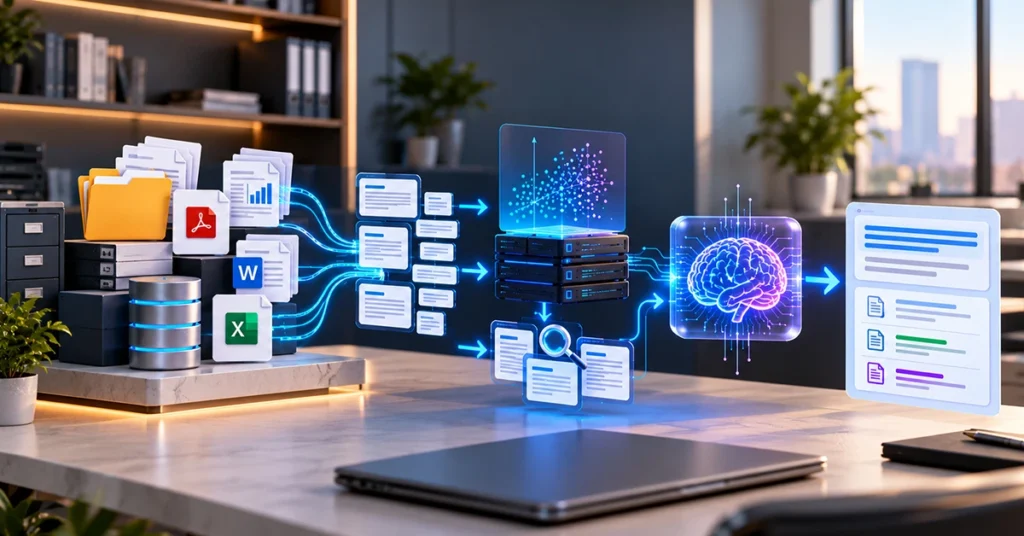
Hook Employees often ask the same questions about HR policies, contracts, pricing, product documents, or technical manuals. Yet the answers remain scattered across SharePoint, PDFs, cloud drives, databases, and internal wikis, making simple information difficult to find quickly. Introduction A Retrieval-Augmented Generation (RAG) system connects an LLM with a company’s internal knowledge. It retrieves relevant company information and uses it as context to generate grounded answers. Building one requires more than connecting documents to an AI model. Companies also need clean data, effective retrieval, access controls, testing, monitoring, and regular updates. Key Takeaways Here is a quick look at the main things you will learn in this guide: How to identify useful internal knowledge for RAG. How to clean, structure, chunk, and index company documents. How vector, keyword, hybrid search, metadata, and reranking work. How to protect restricted company information. How to test, monitor, and update the system. Table of Contents Define What Your Company RAG System Must Answer Audit and Prepare Your Internal Knowledge Choose the Right Data Sources and Retrieval Architecture Clean and Structure Company Documents Before Indexing Chunk Internal Documents for Better Retrieval Create Embeddings and Build the Knowledge Index Combine Keyword, Vector and Hybrid Search Connect Retrieved Knowledge to the LLM Protect Internal Data With Access Controls Test RAG Accuracy Before Going Live Monitor Answers, Costs and Knowledge Updates Move From Prototype to a Production RAG System Define What Your Company RAG System Must Answer Start with the questions employees need answered most often. These may involve HR policies, technical documents, contracts, product information, pricing, or compliance records. Define the users and knowledge scope at the same time. This helps determine the required sources, permissions, retrieval rules, and testing criteria. Audit and Prepare Your Internal Knowledge List every source containing relevant company information before building the retrieval layer. Include document repositories, databases, wikis, cloud storage, and business systems. Review each source for accuracy and relevance. Remove outdated files, duplicates, conflicting versions, and content without clear ownership. Map Data Sources List SharePoint, cloud drives, wikis, databases, CRM systems, and document repositories. Remove Outdated Content Archive old policies, procedures, manuals, and superseded versions. Classify Sensitive Data Separate internal, confidential, financial, employee, customer, and restricted information. Assign Content Owners Identify who reviews and updates each important knowledge source. Choose the Right Data Sources and Retrieval Architecture A typical RAG flow moves from data ingestion to processing, chunking, embeddings, indexing, retrieval, and answer generation. Choose the architecture based on data volume, document types, update frequency, security needs, and query volume. Clean and Structure Company Documents Before Indexing Raw files often contain repeated headers, broken tables, duplicate text, and irrelevant formatting. Clean these elements before indexing. Preserve titles, headings, dates, versions, authors, departments, and source locations because they provide useful retrieval context. Remove Repeated Text: Delete unnecessary headers and footers. Preserve Structure: Keep headings and section relationships. Process Tables: Extract table information accurately. Keep Document Details: Retain titles, dates, and versions. Record Ownership: Store authors and responsible teams. Save Source Locations: Keep links or identifiers for original documents. Chunk Internal Documents for Better Retrieval Chunking divides large documents into smaller searchable sections. Each chunk should contain enough context while staying focused. Use document structure to guide chunking. Policies, contracts, manuals, FAQs, and reports may require different chunking methods. Keep Related Information Together Keep connected requirements, definitions, exceptions, and explanations in the same chunk. Follow Document Structure Use headings, paragraphs, tables, and logical sections as boundaries. Add Chunk Metadata Store the document name, department, date, version, category, and access information. Test Chunk Size Compare different chunk sizes and overlap settings before selecting the final approach. Create Embeddings and Build the Knowledge Index Embeddings convert text into numerical representations that help the system find semantically related content. Store embeddings with metadata and source references so retrieved information can connect back to its original document. Choose an Embedding Model: Match the model to your content and language needs. Generate Embeddings: Create vectors for approved document chunks. Store Metadata: Attach relevant attributes to each chunk. Keep Source IDs: Preserve document and section references. Track Versions: Record the current document version. Re-index Changes: Update the index when approved content changes. Combine Keyword, Vector and Hybrid Search Vector search finds content based on meaning, while keyword search handles exact terms. Both can be useful for internal company information. Hybrid search combines these approaches, while reranking can prioritize the most relevant results before they reach the LLM. Use Vector Search Find semantically similar information despite different wording. Use Keyword Search Find exact names, codes, identifiers, and technical terms. Apply Metadata Filters Filter results by department, date, document type, region, or version. Rerank Results Reorder retrieved passages based on their relevance to the question. Connect Retrieved Knowledge to the LLM The system sends relevant retrieved passages to the LLM as context. The model then uses this information to generate the response. Set clear instructions for using sources and handling missing information. This helps reduce unsupported answers. Pass Relevant Context: Send only useful retrieved content. Use Company Sources: Instruct the model to rely on supplied evidence. Avoid Unsupported Claims: Tell it not to invent missing information. Handle Conflicts: Define how conflicting sources should be treated. Include Citations: Provide document or source references. Set Response Rules: Use a consistent answer format. Protect Internal Data With Access Controls Internal RAG systems may contain confidential employee, financial, customer, contract, and business information. Retrieval must follow existing data permissions. Check authorization before restricted content reaches the LLM. User identity, document permissions, and retrieval filters should work together. Connect User Identity Use the company’s identity system to identify the requesting user. Store Access Rules Associate documents and chunks with approved users, groups, or roles. Filter Retrieved Content Remove unauthorized content before sending results to the LLM. Maintain Access Logs Record relevant access and retrieval events for security review. Test RAG Accuracy Before Going Live A fluent answer does not prove that retrieval worked correctly. Test the retrieved content and generated answer separately. Build a […]

Immigration Services

EU Blue Card vs National Work Permit: What Employers Need to Compare

Hook An employer finds a highly qualified candidate outside the EU and discovers that the candidate may qualify for both an EU Blue Card and a national work permit. The cheaper, faster, or more flexible route can differ based on the country, role, salary, qualifications, and future hiring plans. The right comparison starts with the complete employment and immigration picture, not one application fee or processing estimate. Introduction Employers should compare eligibility, salary rules, qualifications, labour market checks, employer duties, mobility, family rights, renewal requirements, and future relocation options. The EU Blue Card follows a common EU framework in 25 of the 27 EU Member States, while Denmark and Ireland operate outside that framework. Individual countries still control applications and many implementation details. National work permits can provide routes that suit roles or candidates who do not meet Blue Card conditions. Employers therefore need to review the exact national scheme alongside the Blue Card requirements before filing. This guide compares the factors employers should review before choosing an immigration route for an international hire. Key Takeaways Here is a quick look at the main points covered in this guide: EU Blue Card rules follow a common EU framework but still vary by country. National permits can offer different eligibility and salary conditions. Employer costs include more than government application fees. Mobility and future hiring plans can change which route makes sense. Employers should check country-specific rules before filing. Table of Contents Start With the Job and Candidate Compare EU Blue Card and National Permit Requirements Check Salary Rules Before Choosing the Route Compare Qualification and Experience Requirements Compare Employer Checks and Responsibilities Measure Processing Time, Cost, and Administrative Work Consider Job Changes and Employee Mobility Compare Family Rights and Long-Term Residence See How the Rules Differ Across EU Countries Know When a National Permit May Fit Better Plan for Renewals, Compliance, and Employer Changes EU Hiring vs UK and US Work Authorization Employer Comparison Checklist FAQs Start With the Job and Candidate Begin with the actual role, candidate profile, and destination country. These three factors determine which immigration routes deserve review. Define the Job Confirm the occupation, duties, salary, contract length, and work location. Check the Candidate Review nationality, qualifications, professional experience, and current immigration status. Confirm the Country Identify the Member State because national implementation can change the application requirements. Map the Hiring Plan Consider future transfers, additional hires, family relocation, and long-term workforce needs. Compare EU Blue Card and National Permit Requirements The EU Blue Card provides a common framework for highly qualified non-EU workers, but national authorities handle applications and implementation. Some countries also offer national permits for highly qualified workers. Factor EU Blue Card National Work Permit Legal framework EU directive plus national implementation National law Eligible workers Highly qualified workers Depends on country and permit Salary National Blue Card threshold National rules Qualifications Higher qualifications or qualifying experience where permitted Varies Contract Generally at least 6 months Depends on route Employer requirements Country-specific Country-specific Mobility EU mobility framework Usually more country-specific Family rights Common framework with national implementation Depends on national scheme The Blue Card requires a work contract or binding job offer for highly qualified employment for at least six months, subject to the Directive’s conditions. Check Salary Rules Before Choosing the Route Salary can determine eligibility, but employers should compare the applicable threshold with the complete employment package. Check the Blue Card Threshold Each participating country sets the salary threshold within the EU framework. Check the National Threshold National permits can use different salary requirements and calculation methods. Review the Actual Contract Compare gross salary, contract duration, working hours, and other required employment terms. Check Special Thresholds Some countries apply different Blue Card thresholds for specific occupations or shortage areas under national rules. Compare Qualification and Experience Requirements The Blue Card generally requires higher professional qualifications, while some routes can accept qualifying professional experience under national implementation. Education: Check the required higher education qualification. Professional Experience: Some countries recognise qualifying experience for eligible occupations. Regulated Professions: Confirm professional recognition and authorisation before filing. Job Match: Ensure the qualification or experience relates to the proposed employment. Document Evidence: Prepare diplomas, certificates, employment records, and required translations. National Rules: Check the exact qualification rules used by the destination country. The EU framework allows relevant professional experience to satisfy the qualification condition in specified circumstances, particularly where national rules recognise that experience. Compare Employer Checks and Responsibilities Employers should identify every verification and compliance duty before selecting the route. These duties can affect preparation time and internal workload. Labour Market Checks Some national routes require employers to show that local or EU workers cannot fill the position. Specific Blue Card rules can also allow certain labour market checks under national implementation. Employer Eligibility Confirm that the business meets the sponsorship or employment conditions required by the destination country. Document Verification Prepare employment contracts, company documents, salary evidence, qualification records, and other supporting documents. Compliance Duties Maintain accurate employment records and follow notification, renewal, salary, and immigration requirements after approval. Measure Processing Time, Cost, and Administrative Work Application speed and price can influence hiring plans, but employers should calculate the complete administrative workload. Cost or Time Factor What to Compare Government fee Application and permit fees Legal support Immigration counsel or professional assistance Document costs Translation, certification, and recognition Employer work HR preparation and filing time Processing period Official processing stages Visa costs Entry visa costs where applicable Renewal cost Future extension and document expenses Compliance work Ongoing notifications and recordkeeping The EU Blue Card application goes to the competent national authority in the Member State where the worker will work. Countries can apply their own procedures and fees. Consider Job Changes and Employee Mobility Mobility can become important when an employer operates in several European markets. The Blue Card provides a structured mobility framework, subject to specific conditions. First 12 Months: The first Member State can require notification of employer changes and can apply certain […]

Actuarial & Valuation

How Pension Discount Rate Changes Affect Your Balance Sheet

For companies that sponsor defined benefit pension plans, the discount rate is one of the most consequential assumptions in the entire financial statement, and one of the least understood outside the actuarial and finance functions. Under both ASC 715 in the US and IAS 19 across the UK and EU, a small change in this single rate can move pension obligations, equity, and reported expense by material amounts, even when the underlying plan design and workforce have not changed at all. This guide breaks down exactly how discount rate changes flow through to your balance sheet so you can scale your success without the stress. Key Takeaways Here is a quick look at the main things you will learn in this guide: Why the pension discount rate is set by bond markets, not by company or actuarial choice How a rate change moves through the balance sheet, equity, and income statement differently under ASC 715 and IAS 19 Why funded status can improve even when a plan’s investment performance is unremarkable How to read a discount rate sensitivity disclosure and use it for planning What finance and HR teams should actually do when rates move significantly Table of Contents Why the Discount Rate Matters So Much What Sets the Discount Rate How a Rate Change Moves the Liability Where the Impact Lands: ASC 715 Versus IAS 19 Funded Status and What It Really Reflects Duration: Why Some Plans Move More Than Others A Worked Example Reading the Sensitivity Disclosure What This Means for Contributions and Funding Strategy What Finance and HR Teams Should Actually Do Common Misunderstandings to Avoid Conclusion FAQs Why the Discount Rate Matters So Much A defined benefit pension obligation is, at its core, a long stream of future cash payments to retirees stretching out decades. To report that obligation as a single number on today’s balance sheet, accounting standards require it to be discounted back to present value, and the rate used for that discounting is the pension discount rate. Because pension liabilities are often the largest single financial obligation on an industrial or legacy employer’s balance sheet, even a modest change in that one assumption can move reported figures by an amount that dwarfs the year’s actual operating results. This matters beyond pure disclosure. Funded status affects covenant calculations, credit ratings, and how much a company may need to contribute to the plan in future years. A rate move that has nothing to do with how the business performed can still influence how lenders, rating agencies, and the board interpret the company’s financial position. What Sets the Discount Rate The discount rate is not a management estimate chosen to flatter results. Both major standards tie it directly to observable bond market data at the measurement date. The ASC 715 Approach in the US Under ASC 715, the discount rate must reflect the yields available on high-quality, typically AA-rated, corporate bonds with cash flows that match the timing of the plan’s expected benefit payments. The rate must be reassessed at each measurement date using current market information, and rolling forward an older bond portfolio’s yield is generally not considered appropriate. The IAS 19 Approach in the UK and EU IAS 19 similarly requires the discount rate to be based on the market yields of high-quality corporate bonds, generally interpreted as AA-rated or equivalent, with a currency and term consistent with the plan’s obligations. In the UK, many plan sponsors and their actuaries use a single equivalent discount rate derived from an AA-rated corporate bond yield curve matched against the plan’s projected cashflows. Where a jurisdiction lacks a sufficiently deep corporate bond market, IAS 19 requires the use of government bond yields instead, with no added risk premium, which is one of the more notable technical differences from the US approach. The Common Thread In both frameworks, the rate is essentially handed to the company by the bond market on the measurement date. Neither management nor the actuary is selecting a number to achieve a particular reported outcome. That is precisely why the liability can move so significantly from one year to the next purely because of interest rate conditions. How a Rate Change Moves the Liability The mechanics work the same way a bond’s price moves inversely to interest rates, because a pension obligation is fundamentally a very long-duration liability. When the discount rate rises, the present value of future benefit payments falls, because each future dollar owed is worth less today when discounted at a higher rate. This means the projected benefit obligation, or defined benefit obligation under IAS 19, decreases, and funded status improves, all else being equal. When the discount rate falls, the opposite happens. Future payments are discounted at a lower rate, so their present value rises, the liability grows, and funded status deteriorates, again without any change in the actual benefits promised or the plan’s investment performance. This relationship explains a pattern many finance teams have observed over the past few years. As benchmark interest rates rose sharply from the near-zero environment of the early 2020s, discount rates for large corporate plans climbed from roughly the 2% to 3% range up toward the 5% to 5.5% range by the turn of 2025 into 2026, and pension liabilities across the corporate universe compressed sharply as a direct result, independent of how well plan assets performed. Where the Impact Lands: ASC 715 Versus IAS 19 While the underlying mechanics are similar, the two standards handle where the resulting gain or loss shows up quite differently, and this distinction matters for how the change actually reads in the financial statements. Under US GAAP Under ASC 715, actuarial gains and losses arising from discount rate changes are generally recognised in other comprehensive income first, then amortised into net periodic pension cost over time, subject to a corridor approach in many cases. This tends to smooth the income statement impact of rate volatility, even though the balance sheet itself reflects the full remeasured liability immediately. […]

Market Research

TAM vs SAM vs SOM: How to Calculate Your Addressable Market

A business needs more than a large industry number to understand its growth opportunity. Before launching a product, entering a new market, expanding into another region, or presenting a business plan to investors, management needs to know how many customers actually fit the offering and how much revenue those customers represent. This is where TAM, SAM, and SOM provide a clear market-sizing framework. Total Addressable Market (TAM) measures the full revenue opportunity available across the relevant market. Serviceable Available Market (SAM) narrows that opportunity to the customers the business can actually serve based on its product, geography, customer segment, and business model. Serviceable Obtainable Market (SOM) takes the analysis further by estimating the portion of SAM the business can realistically capture. The distinction matters because a large TAM does not automatically translate into sales. A company might operate in a $1 billion market but target only a specific customer segment in two cities. Its realistic revenue opportunity will be far smaller than the headline industry figure. Calculating TAM, SAM, and SOM separates the theoretical market opportunity from the market the business can target and the revenue it has a realistic path to capture. Key Takeaways TAM measures the total potential revenue opportunity within a defined market. SAM measures the portion of TAM that fits the company’s offering, geography, and target customers. SOM measures the realistic share of SAM the business expects to capture within a defined period. Market sizing requires reliable customer, pricing, industry, and competitor data. Top-down analysis provides a broad market perspective, while bottom-up analysis connects market size to actual customers and revenue. TAM helps communicate long-term opportunity, while SAM and SOM support practical sales and growth planning. Market-share assumptions should reflect competition, sales capacity, pricing, customer acquisition, and available resources. Table of Contents What Are TAM, SAM, and SOM? TAM vs SAM vs SOM: Understanding the Difference How to Calculate TAM How to Calculate SAM How to Calculate SOM Top-Down vs Bottom-Up Market Sizing Worked TAM, SAM, and SOM Example Common Market-Sizing Mistakes How to Build a More Reliable Market Estimate Read More FAQs Final Thoughts What Are TAM, SAM, and SOM? TAM, SAM, and SOM represent three increasingly specific levels of market opportunity. Each answers a different business question. Total Addressable Market (TAM) TAM asks: How large is the entire relevant market? TAM represents the total revenue opportunity available if a business captured every customer that fits its overall market definition. This is the broadest measurement. It does not account for the company’s current sales team, marketing budget, geographic restrictions, competitive position, or operational capacity. For example, a company selling accounting software might define its TAM around all businesses that fit its broad customer category and require accounting technology. The basic formula is: TAM = Total Potential Customers × Average Annual Revenue per Customer If 500,000 potential businesses spend an average of $1,000 per year on the relevant product: TAM = 500,000 × $1,000 = $500 million The resulting $500 million represents the theoretical revenue opportunity across the defined market. Serviceable Available Market (SAM) SAM asks: How much of the total market fits our actual offering and reach? SAM filters TAM based on the company’s product, geographic coverage, customer profile, pricing, distribution model, and service capabilities. Suppose the accounting software company operates only in the United States and targets businesses with fewer than 100 employees. The company’s SAM excludes customers outside that geography and businesses outside its target size range. If 100,000 businesses meet those criteria and the average annual customer value is $1,000: SAM = 100,000 × $1,000 = $100 million The company therefore has a $100 million serviceable market within its current commercial scope. Serviceable Obtainable Market (SOM) SOM asks: How much of our serviceable market can we realistically capture? SOM is the most practical measure for revenue planning. It accounts for the company’s competitive position, sales capacity, marketing resources, pricing, customer acquisition, distribution, and growth strategy. The simplified formula is: SOM = SAM × Realistic Market Share If SAM equals $100 million and the company has a realistic path to 2% market share: SOM = $100 million × 2% = $2 million This $2 million figure provides a more realistic basis for a revenue target than the $500 million TAM. TAM vs SAM vs SOM: Understanding the Difference The three measurements work as a narrowing funnel. Measure Business Question What It Represents TAM How large is the total opportunity? Entire relevant market SAM Which part of that market fits our offering? Targetable market SOM What portion can we realistically capture? Obtainable market Consider a business with a $500 million TAM, a $100 million SAM, and a $2 million SOM. The figures are not contradictory. Each serves a different purpose. TAM demonstrates the overall scale of the market. SAM identifies the commercially relevant segment. SOM establishes the realistic capture opportunity. This distinction becomes especially important when preparing investor presentations and business plans. Presenting a large TAM without explaining the SAM and SOM often creates an inflated view of the opportunity. A credible market-sizing model shows exactly how the business moves from the broad market to its realistic revenue opportunity. How to Calculate TAM TAM calculation starts with a precise market definition. The business needs to establish exactly what product, customer category, geography, and revenue stream it is measuring. 1. Define the relevant market Avoid broad labels such as “software,” “consulting,” or “healthcare.” Define the specific product or service category and the customer problem it addresses. A business selling payroll software to small and medium-sized companies should calculate its market around the relevant payroll software customer base, not the entire enterprise software industry. 2. Determine the total potential customer base Estimate the number of businesses or consumers that fit the broad market definition. Useful sources include: Government statistics Industry associations Company databases Market research reports Trade publications Business registries Internal customer research 3. Establish average annual customer value Determine how much revenue an average customer generates over a year. For subscription businesses, this could […]

IT Consulting & Outsourcing, Uncategorized

IT Outsourcing vs In-House IT: How to Compare Total Operating Costs

IT costs rarely stop at salaries and software bills. An in-house team may look cheaper because it sits on the payroll you already know, while outsourcing may appear expensive because the vendor invoice is easy to see. The real comparison includes hiring, benefits, infrastructure, software, training, management, downtime, compliance, and support. Introduction Businesses in the EU, UK, and USA often compare in-house IT with outsourcing when they need reliable technology support without letting operating costs grow too quickly. The challenge is that these two models are billed differently. An internal team creates many separate expenses, while an outsourced provider may combine several services into one monthly fee. A useful comparison should look beyond the visible price and calculate the total operating cost of each model. This includes direct spending, indirect costs, risk-related expenses, and the resources required to manage IT operations. This article cuts through the fluff to show you how to compare IT outsourcing and in-house IT costs so you can choose a structure that fits your business as it grows. Key Takeaways Here is a quick look at the main things you will learn in this guide: Compare salaries with the full cost of employing an internal IT team. Include software, hardware, cloud, security, training, and support expenses. Calculate outsourcing costs using the complete vendor contract, not just the monthly fee. Account for downtime, recruitment, management time, and compliance work. Review EU, UK, and US tax and accounting considerations before comparing final costs. Table of Contents What Total IT Operating Cost Really Means Calculating the Cost of In-House IT Calculating the Cost of IT Outsourcing Direct and Indirect Costs to Compare EU, UK, and USA Cost Considerations A Practical IT Cost Comparison Formula When In-House IT May Cost More When Outsourcing May Cost More How to Build a Three-Year Cost Comparison What Total IT Operating Cost Really Means Total IT operating cost is the amount a business spends to run, maintain, secure, and support its technology environment over a set period. Many companies start with the wrong figure. They compare an employee’s annual salary against an IT vendor’s annual contract and assume the lower number represents the lower cost. That calculation leaves out several expenses. For an in-house team, the actual cost can include: Salaries and employer payroll costs Health insurance and employee benefits Paid leave and retirement contributions Recruitment and onboarding Office space and equipment Hardware replacement Software licences Cloud infrastructure Cybersecurity tools Training and certifications IT management After-hours support Temporary staff during absences An outsourced model has a different cost structure. A contract may include help desk support, monitoring, maintenance, security, cloud administration, and backup services. However, businesses still need to check for additional charges, setup fees, project costs, hardware purchases, and services outside the contract. The goal is to compare equivalent services over the same period. Calculating the Cost of In-House IT Start by calculating the fully loaded employment cost rather than salary alone. Suppose a US business employs two IT specialists at $85,000 each. The annual payroll is $170,000, but the business does not actually spend only $170,000. Payroll taxes, benefits, recruitment, equipment, training, and other costs can raise the annual figure significantly. The same principle applies in the UK and EU. Employer National Insurance in the UK, statutory employment costs, pension contributions, paid leave, and employee benefits can increase the cost beyond base salary. EU employment expenses also differ by country, so businesses should use the applicable local employer contributions instead of applying one EU-wide rate. Infrastructure creates another cost layer. An internal team may need laptops, servers, networking equipment, endpoint protection, monitoring platforms, ticketing software, identity management tools, and backup systems. Hardware also has a replacement cycle, which means the annual budget should account for depreciation or planned replacement spending. Training is another frequently missed item. Technology changes quickly, and internal employees may need certifications, courses, conferences, security training, or specialist contractors. Management time should also be included. If an operations manager or IT director spends several hours each week handling recruitment, vendor management, escalations, budgeting, and staff scheduling, that time has an economic cost. Calculating the Cost of IT Outsourcing Outsourcing costs usually start with the provider’s contract. A business may pay a fixed monthly amount per user, device, server, workload, or service package. Some providers use a hybrid structure with a fixed base fee plus charges for projects or additional support. Start by identifying what the recurring fee covers. Ask for a breakdown of: Help desk support Remote and on-site support Network monitoring Cybersecurity Cloud administration Backup and disaster recovery Software management Device management Compliance support Reporting Service management Then identify what is excluded. A contract can appear inexpensive until a business discovers separate charges for emergency support, new employee onboarding, hardware, software licences, travel, after-hours assistance, or project work. Setup costs also matter. Moving systems to a provider may require migration, documentation, security assessment, data transfer, or integration work. Businesses should also review contract terms. Minimum commitments, annual price increases, usage limits, termination charges, and additional service fees can affect the total cost over several years. A monthly fee of $10,000, for example, represents $120,000 per year before additional charges. A three-year contract at the same base price would total $360,000. That number becomes more useful when compared against the full three-year cost of maintaining an equivalent internal function. Direct and Indirect Costs to Compare A reliable comparison separates direct and indirect costs. Direct costs are easier to identify. They include salaries, vendor fees, software subscriptions, equipment, cloud services, and support contracts. Indirect costs can be harder to measure but may have a major effect on the final figure. Recruitment and Staff Turnover Hiring IT professionals can take weeks or months. Recruitment agencies, advertising, interviews, onboarding, and background checks create costs. Turnover can add more expense. When an experienced employee leaves, the business may lose operational knowledge and spend additional time finding a replacement. Downtime IT downtime can affect sales, customer service, production, and employee productivity. The cost […]

Sustainability & ESG

What Is Double Materiality and How Do Companies Apply It in ESG Reporting?

A company can have a small environmental footprint today and still face major financial risks from climate change, supply chain pressure, or new reporting rules. At the same time, its own activities may affect workers, communities, customers, and the environment. Traditional materiality often focuses on what can affect the business. Double materiality asks companies to look in both directions. Introduction ESG reporting is moving beyond a simple list of environmental, social, and governance metrics. Under the European Sustainability Reporting Standards (ESRS), companies in scope of the Corporate Sustainability Reporting Directive (CSRD) use a double materiality perspective to identify the sustainability matters that need to be reported. EFRAG explains that this means assessing both impact materiality and financial materiality. A topic can be material from one perspective or both. This guide explains how double materiality works and how companies can apply it in practice today across markets. Key Takeaways Here is a quick look at the main things you will learn in this guide: Double materiality combines impact and financial materiality. A matter can be material from one perspective or both. Companies should consider relevant value chain relationships. Stakeholder input and evidence support the assessment. Results should connect to ESG disclosures and metrics. Table of Contents What Is Double Materiality? Impact Materiality vs. Financial Materiality Why Double Materiality Matters in ESG Reporting How Companies Conduct a Double Materiality Assessment What Data and Stakeholder Input Should Companies Use? How Double Materiality Supports ESRS Reporting Common Challenges Companies Face How US and UK Companies Should View Double Materiality Practical Example of a Double Materiality Assessment Conclusion: Turning Assessment Results Into Better Reporting FAQs What Is Double Materiality? Double materiality assesses sustainability matters from two connected perspectives. Impact materiality asks how a company affects people and the environment. Financial materiality asks how sustainability-related risks and opportunities can affect the company. EFRAG states that ESRS reporting uses both perspectives. A matter does not have to be material from both sides. Workplace safety, for example, could be material because of its effect on employees even when its current financial effect is limited. A sustainability issue could also create a material financial risk without a comparable direct impact. The approach therefore asks two questions: “How could this issue affect our business?” and “How do our activities affect people and the environment?” It also considers relevant upstream and downstream value chain relationships. Impact Materiality vs. Financial Materiality Impact materiality focuses on the effects a company has on people and the environment. These effects may be actual or potential, positive or negative, and may occur over the short, medium, or long term. A company may assess topics such as emissions, employee health and safety, human rights, product safety, water use, biodiversity, or community impacts. Financial materiality focuses on sustainability-related risks and opportunities that could affect the company’s development, financial position, financial performance, cash flows, access to finance, or cost of capital. The assessment looks across the short, medium, and long term. The two perspectives can overlap. An environmental impact may lead to regulation, higher costs, asset damage, or financing concerns. A workforce issue may affect retention, legal exposure, or operating costs. Companies do not need two isolated exercises. ESRS guidance says the assessment should reflect both perspectives and their connections. Why Double Materiality Matters in ESG Reporting Double materiality matters because ESG reporting is increasingly connected to how companies explain their strategy, governance, risks, and performance. Under the ESRS framework, the sustainability statement is based on material sustainability impacts, risks, and opportunities identified through the materiality assessment. The process can improve internal understanding of sustainability issues. Finance, risk, legal, operations, procurement, HR, and sustainability teams can see how these matters connect with business activities. For companies with European reporting obligations, the assessment supports the selection of information included in the sustainability statement. EFRAG’s 2026 State of Play report reviewed 905 assured FY2025 sustainability statements and included analysis of double materiality methods, showing how practice is developing. How Companies Conduct a Double Materiality Assessment A practical assessment can be organized into several stages. 1. Understand the company and its context Start with the business model, strategy, activities, markets, products, services, locations, workforce, assets, and business relationships. Consider the company’s legal structure and the nature of its operations. Companies should review the regulatory and market context because different business models face different sustainability matters. 2. Identify sustainability matters Build a broad list of relevant ESG matters before deciding which ones are material. ESRS 1 provides a sustainability matters framework covering environmental, social, and governance topics. Companies can also identify entity-specific matters that are relevant to their own circumstances. Sources may include ESG reports, risk registers, environmental data, incident reports, supplier information, research, and regulatory developments. 3. Identify impacts, risks, and opportunities For each matter, identify actual and potential impacts and consider the related risks and opportunities. Map where these arise in the company’s own operations and across relevant value chain relationships. For impact materiality, companies can consider the scale, scope, and characteristics of impacts. Potential negative impacts may also require consideration of likelihood. For financial materiality, companies assess the size and likelihood of financial effects and the time horizon over which those effects may occur. 4. Gather stakeholder input Stakeholder engagement can provide useful evidence. Relevant groups may include employees, workers, suppliers, customers, consumers, local communities, public authorities, investors, lenders, and other affected parties. Stakeholder input is one source of evidence that can help the company understand impacts, risks, and expectations. 5. Score and evaluate matters Companies can use a documented scoring method to assess impacts and financial effects. ESRS does not prescribe one universal scoring model. The company should document its criteria, evidence, assumptions, thresholds, and judgments. EFRAG guidance says the assessment should reflect the company’s specific facts and circumstances. 6. Validate the results Senior management and relevant governance bodies should review the assessment process and results. The company should check for missing matters and confirm that conclusions are supported by evidence. The assessment should link sustainability matters to […]

Digital Marketing & SEO

How to Find SEO Content Gaps Your Competitors Are Missing

Every industry has questions that searchers ask again and again but few websites answer well. Those unanswered or poorly answered questions are content gaps, and they are some of the most reliable opportunities in search. In the US, UK, and EU, where competition is high and audiences differ by state, country, and language, finding the right gaps matters more than publishing more articles. This guide breaks down the exact steps to find and fill content gaps so you can scale your success without the stress. Key Takeaways Here is a quick look at the main things you will learn in this guide: What content gaps are, and the different types that can hold your site back How to identify your true search competitors and compare what they cover with what you do How to look beyond keyword lists by studying customer questions, results pages, and AI-generated answers How to score and prioritise gaps so you spend time on the ones that matter How to create, measure, and repeat the process every quarter Table of Contents What an SEO Content Gap Really Is The Main Types of Content Gaps Set Up Your Analysis and Choose the Right Competitors Run a Keyword and Topic Gap Analysis Look Beyond Keywords Audit Your Existing Content Score and Prioritise the Gaps Create Content That Fills the Gap Measure Results and Repeat Your Content Gap Checklist Conclusion FAQs What an SEO Content Gap Really Is A content gap is a difference between what searchers want and what your website provides. It might be a topic you never covered, a question you answered too briefly, a format your audience prefers but you do not offer, or a page that exists but is weaker than what competitors publish. Finding gaps is not about copying rivals. It is about noticing where demand exists and where the current results fall short. A gap is only worth filling if it connects to your business. A topic with high search volume but no link to your services will bring visitors who never become customers. The best opportunities sit where three things overlap: real search demand, a clear fit with what you offer, and a realistic chance of producing something better than what already ranks. The Main Types of Content Gaps Gaps come in several forms, and knowing them helps you spot more of them. Topic Gaps These are subjects that competitors cover and you do not. For example, a US accounting firm may rank for general tax deadlines but have nothing on estimated tax payments for freelancers, while its competitors do. Search Intent Gaps You may cover the topic, but not the way searchers want it. People searching for a “how to” want steps, people comparing options want a comparison, and people ready to act want pricing and next steps. A page that explains theory when the searcher wants a checklist will lose to one that gives the checklist. Format Gaps Some queries are best answered with a calculator, template, video, table, or downloadable guide. If every top result includes a tool or visual and yours is plain text, that is a gap. Depth and Quality Gaps Your page may be shorter, older, less accurate, or less useful than the leaders. It might skip common follow-up questions, lack examples, or cite no reliable sources. Audience and Location Gaps A page written only for one audience can miss others. A US reader may need state-specific rules, a UK reader may look for HMRC processes and amounts in GBP, and a reader in the EU may need country-specific VAT rules in EUR and content in their own language. Serving each properly opens doors that generic pages cannot. Freshness Gaps Rules, prices, and tools change. If competitors update their guidance and yours still reflects last year’s rules, searchers and search engines will prefer the newer page. Set Up Your Analysis and Choose the Right Competitors Before you start comparing, decide what success looks like. Set a clear goal, such as more qualified enquiries, more newsletter sign-ups, or greater visibility for a service line. Define your audience and the countries or regions you serve. Then gather the data you will need: Search Console data showing the queries and pages that already bring impressions and clicks Analytics data showing which pages lead to enquiries or sales A full inventory of your existing content, with topics, dates, and performance Questions collected from sales calls, support emails, live chat, and your own site search A short list of your main topics, services, and products Your search competitors are not always your business competitors. Search each of your core topics and note who appears on the first page. You will often see publishers, industry bodies, government sites, forums, and comparison sites alongside direct rivals. Choose three to five competitors that you can realistically challenge, and include at least one that is smaller and growing fast, since it often reveals newer opportunities. Run a Keyword and Topic Gap Analysis Once you have your competitors, work through this process: Use the keyword gap feature in a research tool, or a manual review, to list terms where competitors rank and you do not. Group those terms into topics instead of treating each phrase as a separate article, since one page can often answer many related searches. Remove terms that do not match your services, audience, or regions. Check the intent behind each group by reading the top results and noting whether they are guides, comparisons, tools, or product pages. Review competitors’ site structure, including their main categories, resource hubs, and the pages they promote most, to see which topics they treat as priorities. Look for topics where competitors have only one thin page, or none, which often signals an opening. Record every gap in a shared spreadsheet with the topic, intent, competitor examples, and your existing page, if any. Look Beyond Keywords Keyword tools show what people type, but not always what they need. Add these sources to find gaps that spreadsheets […]

HR, Payroll & Recruitment

How to Hire Your First Employee: A Small Business Guide

Hiring your first employee is a major step for a small business. Until now, you may have handled sales, customer service, bookkeeping, operations, and administrative work yourself. Bringing in another person can free up your time, but it also creates new payroll, tax, legal, and management responsibilities. A careful hiring process helps you avoid costly mistakes and gives your new team member a clear start. Introduction Your first hire can change how your business operates. The right employee can take recurring work off your plate, improve customer service, and give you more time to focus on revenue and business development. But hiring is more than posting a job and choosing a candidate. U.S. employers need to think about worker classification, an Employer Identification Number (EIN), Form I-9, Form W-4, payroll taxes, wage rules, state requirements, benefits, records, and workplace policies. The IRS states that businesses with employees have specific withholding, reporting, and employment tax duties. This guide breaks down the main steps for hiring your first employee so you can grow your team with fewer surprises. Key Takeaways Here is a quick look at the main things you will learn in this guide: How to decide if your business is ready for its first employee. How to define the role, pay range, and hiring budget. Which federal forms and payroll steps U.S. employers need to handle. Why state and local employment rules matter alongside federal law. How to prepare your new employee for a productive first month. Table of Contents Decide Why You Need to Hire Calculate the Real Cost of Your First Employee Define the Job Before You Advertise Choose Employee or Independent Contractor Set Up Your Employer Requirements Write and Publish the Job Description Screen and Interview Candidates Make the Job Offer Complete New-Hire Paperwork Set Up Payroll and Employment Taxes Prepare the Workplace Before Day One Build a Strong First 30 Days Hiring Considerations for Europe and the UK Common First-Time Hiring Mistakes First Employee Hiring Checklist 1. Decide Why You Need to Hire Before creating a job post, identify the business problem you want the employee to solve. A first hire should have a clear purpose. Maybe you spend 15 hours each week answering customer emails. Perhaps bookkeeping, scheduling, order processing, sales outreach, or technical work is taking time away from higher-value tasks. Write down the work you want to transfer. Then estimate: How many hours the work takes each week. Which tasks require your direct involvement. Which tasks could be taught to another person. What business activities you could focus on after delegating the work. What skills the new employee must have from day one. This exercise also helps you decide between a full-time employee, part-time employee, or another staffing arrangement. 2. Calculate the Real Cost of Your First Employee Salary is only one part of the hiring budget. Your total employment cost may include: Base wages or salary Employer payroll taxes State unemployment taxes Workers’ compensation insurance Health or other benefits Retirement contributions Paid leave Payroll software Recruiting costs Equipment Training Office or remote-work expenses Federal employment taxes can include federal income tax withholding, Social Security, Medicare, and federal unemployment tax. Employers generally pay the employer share of Social Security and Medicare taxes and handle the required withholding and reporting. Create a monthly and annual hiring budget before you publish the position. For example, a $50,000 annual salary does not mean your business will spend exactly $50,000 on that employee. Your budget should also account for less obvious costs, such as a laptop, software subscriptions, onboarding time, and paid training. 3. Define the Job Before You Advertise A vague role creates vague expectations. Start with a simple job description that explains: Job title: Use a title candidates understand. Main responsibilities: List the work the employee will handle regularly. Required skills: Separate must-have skills from skills that can be learned. Experience: State the experience level you actually need. Working arrangement: Explain whether the role is onsite, hybrid, or remote. Schedule: Include expected working hours and any required flexibility. Pay: State a salary or hourly range where required or appropriate. Reporting line: Explain who the employee will report to. Performance expectations: Give candidates a basic idea of how success will be measured. Keep the description focused on the actual work. A small business does not need a long list of requirements for an entry-level position. 4. Choose Employee or Independent Contractor Before paying someone for work, determine how the worker should be classified. This is not simply a matter of choosing the label that seems easiest. The IRS says businesses must correctly classify workers as employees or independent contractors because the tax responsibilities differ. An employee generally works under the business’s direction and is subject to employment-related rules and payroll requirements. An independent contractor generally operates as a separate business and is responsible for their own tax obligations. Misclassification can create problems involving payroll taxes, wages, benefits, and reporting. If the working relationship is unclear, review the applicable IRS guidance and seek professional tax or legal advice before making the classification. 5. Set Up Your Employer Requirements If you are hiring your first employee in the United States, check that your business has the required employer setup. Get an EIN An Employer Identification Number identifies your business for federal tax purposes. Businesses generally need an EIN to hire employees. If you already have an EIN, verify that your business information is current. Check State Requirements Federal rules are only part of the process. Depending on your location, you may need to register for: State payroll taxes State unemployment insurance Workers’ compensation State new-hire reporting State disability or paid-leave programs Local employment taxes Required workplace notices State requirements can differ significantly, so check the relevant state agencies before hiring. Review Wage and Hour Rules The Fair Labor Standards Act establishes federal minimum wage, overtime, recordkeeping, and youth employment standards. Covered nonexempt employees generally must receive overtime at one and one-half times their regular rate for hours […]

Scroll to Top